Market Overview: Defining the Do It Yourself (DIY) Market Scope
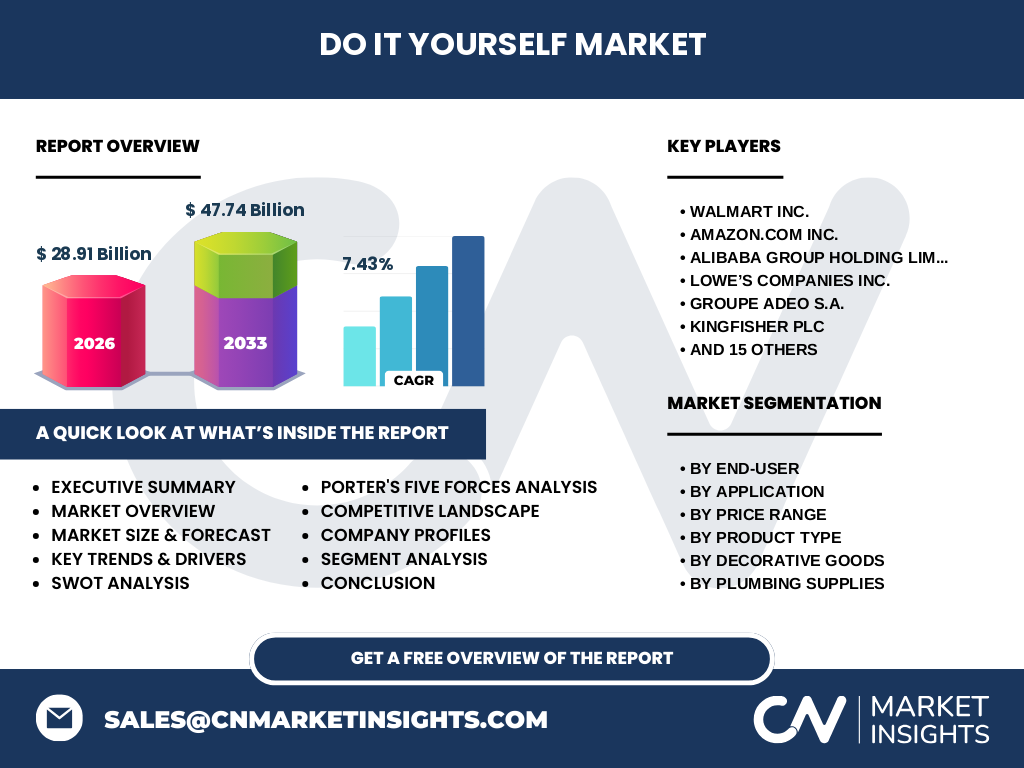
The Do It Yourself (DIY) Market encompasses a vast ecosystem of consumer-led home improvement, repair, and creative projects. Valued at 28.91 Billion in 2026, this sector bridges the gap between raw material manufacturing and end-user execution. It provides essential building blocks, from lumber products to sophisticated power tools, empowering hobbyists and professionals to manage structural maintenance, aesthetic customization, and functional upgrades independently.
Structural Growth Drivers and Market Constraints
Growth is primarily fueled by the rising cost of professional labor, which incentivizes homeowners to undertake repairs themselves. However, the market faces logistical hurdles such as global supply chain disruptions affecting raw material procurement like cement and steel. Opportunities remain strong in smart-home integration, while high interest rates represent a persistent constraint on large-scale renovation budgets, shifting demand toward smaller, high-margin decorative and maintenance projects.
Emerging Trends in the DIY Industry
A core shift is occurring toward sustainability and modular design. Consumers increasingly favor eco-friendly building materials and energy-efficient lighting and electrical products. Furthermore, the rise of digital tutorials has revolutionized the crafts and hobbies segment, allowing amateur users to tackle complex electrical or plumbing repairs that were previously restricted to licensed contractors, thereby expanding the total addressable market for power tools and hardware.
COVID-19 Impact and Recovery Trajectory
The pandemic acted as a catalytic force for the DIY market, as lockdowns redirected disposable income from travel toward home improvement. While supply chains faced massive bottlenecks, the industry has since stabilized. The recovery trajectory is now defined by a permanent shift in consumer behavior; the newfound confidence in managing property maintenance continues to drive steady growth, transitioning from impulsive panic-buying to strategic, value-based home enhancement.
Competitive Landscape and Strategic Dynamics
The market is highly fragmented, with giants like Lowe’s Companies Inc., Home Depot (implied), and Groupe ADEO S.A. exerting significant influence through vast retail networks. Conversely, niche players like MR D.I.Y. Group (M) Berhad focus on high-frequency, affordable hardware. Competitive intensity is high, with major retailers leveraging proprietary distribution networks and advanced e-commerce platforms to counter the logistical reach of Amazon and Alibaba, ensuring local access to essential repair materials.
Executive Summary of Global DIY Market Potential
The Do It Yourself (DIY) Market is poised for substantial expansion, forecasted to reach 47.74 Billion by 2033 from a 2026 valuation of 28.91 Billion. With a robust CAGR of 7.43%, this growth is supported by an aging housing stock requiring constant maintenance and an increasing demographic of tech-savvy hobbyists who prioritize personalization, efficiency, and self-sufficiency over outsourcing labor-intensive property improvements.
Market Forecast: Growth Trajectory from 2027 to 2033
Based on our quantitative modeling, the market will maintain a CAGR of 7.43% through 2033. This consistent upward trend is predicated on urban densification driving demand for compact furniture and smart kitchen and bathroom products. We anticipate the most aggressive growth phase to occur between 2029 and 2031, as digital-first retail platforms optimize logistics and consumer access to premium, specialized equipment at scale.
Segmentation Analysis: End-Users and Applications
The Do It Yourself (DIY) Market serves diverse segments including hobbyists, homeowners, professionals, and students. Home improvement remains the dominant application, leveraging building materials and plumbing supplies. The segment for professionals is particularly notable, as many utilize commercial-grade tools for smaller, specialized tasks. This segmentation allows retailers like Ace Hardware to tailor inventories, balancing high-turnover DIY kits with specialized hardware for seasoned users.
Regional Market Performance Distribution
Geographically, North America and Europe hold the largest market share, driven by a strong culture of property ownership. However, Asia-Pacific is witnessing the fastest growth due to rapid urbanization. Regional performance is heavily influenced by local building codes and regulatory bodies—such as OSHA standards in the U.S. or CE marking regulations in Europe—which dictate the safety specifications for electrical components and building materials.
In-depth Regional Review: Key Geographic Hotspots
In North America, Canadian Tire Corporation and Lowe’s dominate through extensive retail footprints. In contrast, the European market, led by Kingfisher plc and HORNBACH Holding AG, focuses on energy-efficient retrofitting due to stringent regional environmental mandates. These regional dynamics require manufacturers to pivot their supply chains, adjusting for localized consumer preferences, such as specific aesthetic requirements in interior design and unique plumbing fixtures common to historic European infrastructure.
Company Profiles and Strategic Positioning
Industry leaders maintain distinct strategic moats. Amazon and Alibaba capture the e-commerce volume through extensive marketplace reach. Bunnings Group Limited maintains dominance in Oceania through expert-led customer service and inventory depth. Meanwhile, Fastenal Company focuses on industrial-grade hardware, catering to the professional segment of the DIY market. These players balance their market concentration by integrating digital tools with physical, on-the-ground support centers for complex repair inquiries.
Porter's Five Forces Analysis
The DIY market features intense competitive rivalry among established incumbents like OBI Group and B&Q. Supplier power is moderate, balanced by global sourcing, while the threat of substitutes is low, as homeowners cannot easily outsource labor without incurring high costs. New entrants face significant barriers due to logistical capital requirements and the need for established supply chain relationships with major tool manufacturers to maintain competitive price-point tiers.
SWOT Analysis of the DIY Market Ecosystem
The Strengths lie in high consumer demand for customization. Weaknesses include vulnerability to raw material price inflation, such as fluctuating lumber costs. Opportunities are abundant in the smart-home technology sector and DIY kit convenience. Threats include potential economic downturns that suppress discretionary home spending and persistent labor shortages that delay large-scale DIY projects, forcing a shift toward simpler, more affordable maintenance and decoration tasks.
Value Chain Analysis: From Raw Materials to End-Users
The value chain starts with the extraction of raw materials like iron ore and timber, processed into building materials and hand tools. Value is added at the manufacturing stage before reaching distributors or retail giants like Menard Inc. and BAUHAUS AG. The final stage involves the consumer, where digital platforms have increasingly streamlined the path from purchase to project execution, reducing overhead and improving accessibility for the hobbyist segment.
Investment Insights and High-Potential Areas
Investors should prioritize vertically integrated retailers that control both the supply chain of plumbing supplies and the digital interface for customer support. High-potential areas include DIY-friendly smart lighting and modular cabinetry solutions that minimize installation complexity. Companies like Travis Perkins plc offer strong investment potential due to their specialized supply chain focus, which serves as a critical bridge between bulk manufacturing and the growing end-user market.
Conclusion and Key Takeaways
The Do It Yourself (DIY) Market is in a phase of structural transition. With a 7.43% CAGR and a 2033 forecast of 47.74 Billion, the industry is shifting toward integrated retail solutions. Success depends on navigating regulatory hurdles, managing logistical efficiencies, and catering to a consumer base that increasingly demands both quality and convenience for a wide range of home, gardening, and automotive repair projects.
Research Methodology for Market Triangulation
Our baseline estimates are derived from a triangulation methodology that synthesizes global trade registry data, primary interviews with regional store managers, and macroeconomic indicators. We cross-reference quarterly earnings reports from industry leaders like Castorama France SAS and Mitre 10 to ensure accuracy. This multi-layered approach filters out market volatility, providing a reliable foundation for our projections and ensuring our analysis captures the nuanced reality of this 28.91 Billion market.
Scope of the Report: Parameters and Limitations
This report covers the global DIY market across seven key product segments and four primary end-user profiles. It evaluates the impact of retail distribution channels on market penetration. Limitations include potential variations in local building code interpretations and logistical constraints in emerging markets that may influence final market size. The scope focuses exclusively on consumer-oriented DIY products, excluding heavy industrial construction equipment or large-scale commercial real estate developments.
Recent Developments in the DIY Landscape
Strategic moves in the market highlight a push toward digital-physical integration. Recent partnerships between major retailers and smart-home technology providers have streamlined the installation of electrical and lighting products. Furthermore, expansion into new geographical territories by MR D.I.Y. Group and the launch of proprietary premium equipment lines by leading hardware manufacturers demonstrate a proactive effort to capture higher-margin consumer segments, reinforcing the current 7.43% growth trajectory.